The Ibovespa Will Make Room for Depositary Receipts
BRAZIL · MARKETS
Key Facts
- —The change B3 announced on 8 September that Brazilian depositary receipts will become eligible for the Ibovespa.
- —The cap Their combined weight in the theoretical portfolio is limited to 10 percent.
- —The current rule BDRs are not eligible for Ibovespa inclusion at all today.
- —When First half of 2027.
- —The conditions Standard liquidity and representativeness criteria still apply.
- —Who it affects Brazilian companies listed abroad whose Brazilian exposure reaches investors through receipts rather than ordinary shares.
Brazil’s benchmark index has never contained a depositary receipt. From 2027 it can be one tenth of it.
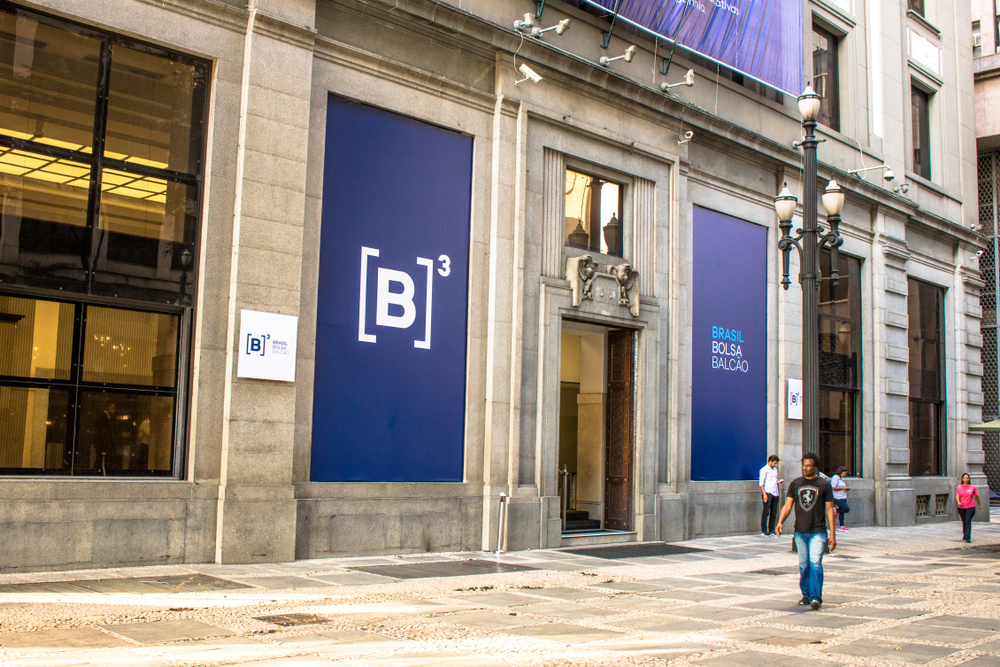
B3 said on 8 September that Brazilian depositary receipts issued by Brazilian companies will become eligible for inclusion in the Ibovespa from the first half of 2027, capped at 10 percent of the index.
What Changes
Today BDRs are not eligible for the Ibovespa at any weight. From the first half of 2027 they will be, subject to the same liquidity and representativeness tests every other constituent must pass.
The joint participation of all BDRs in the theoretical portfolio is capped at 10 percent. That is a ceiling on the category, not on any one issuer.
Why the Rule Existed
The Ibovespa is a measure of the Brazilian equity market. A depositary receipt is a claim on a share listed somewhere else, and including one has always raised the question of whether the index is measuring Brazil or measuring Brazilian exposure wherever it happens to be listed.
That distinction has become harder to hold. A growing number of Brazilian companies have their primary listing abroad, with Brazilian investors reaching them through receipts. Excluding those receipts means the benchmark increasingly excludes companies that are, in every commercial sense, Brazilian.
The 10 percent cap is the compromise. It admits the category without letting it define the index.
Live Market IntelligenceBrazil — Live Market Board
Rio Times · Live Market Intelligence
Brazil — Live Market Board
-0.91%
185,500.88
-0.91%
64,216.98
+0.46%
11,342.39
+1.09%
3,084,547
-0.46%
2,588.25
-0.06%
59,184.75
-0.92%
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| IBOV | 185,500.88 | -0.91% | +21.85% | 187,206.89 | 168,310 | 167,142 | — |
| USD/BRL | 5.16 | +0.01% | -5.13% | 5.16 | 5.18 | 5.14 | — |
| SELIC | 14.00% | — | — | — | — | — | |
| PETR4 | 41.64 | -0.05% | +35.19% | 41.66 | 41.97 | 41.15 | 41,499,400 |
| VALE3 | 72.97 | +0.83% | +30.75% | 72.37 | 73.54 | 72.66 | 17,658,000 |
| ITUB4 | 38.60 | -1.03% | +4.57% | 39.00 | 39.34 | 38.39 | 29,487,800 |
| BBDC4 | 16.85 | +0.36% | +3.50% | 16.79 | 16.90 | 16.67 | 19,416,900 |
| BBAS3 | 19.37 | +0.47% | +0.73% | 19.28 | 19.44 | 19.16 | 11,069,200 |
| B3SA3 | 14.26 | -0.21% | +12.73% | 14.29 | 14.47 | 14.11 | 33,037,800 |
| ABEV3 | 14.89 | -0.80% | +21.91% | 15.01 | 15.07 | 14.81 | 16,453,100 |
| WEGE3 | 47.59 | +0.49% | +29.99% | 47.36 | 48.08 | 47.36 | 3,364,600 |
| PRIO3 | 59.14 | -0.19% | +50.67% | 59.25 | 59.81 | 58.74 | 3,325,600 |
| SUZB3 | 41.33 | +2.35% | -23.55% | 40.38 | 41.48 | 40.35 | 3,914,900 |
| RENT3 | 34.68 | -0.09% | +0.84% | 34.71 | 34.96 | 34.35 | 7,979,100 |
| AZZA3 | 15.89 | -2.63% | -53.76% | 16.32 | 16.42 | 15.82 | 1,330,300 |
| CSNA3 | 4.30 | +0.47% | -42.65% | 4.28 | 4.41 | 4.26 | 10,076,100 |
| GGBR4 | 24.69 | +2.19% | +51.38% | 24.16 | 24.85 | 24.18 | 7,047,600 |
| ENEV3 | 24.21 | -1.38% | +70.49% | 24.55 | 24.64 | 23.99 | 9,297,000 |
What to Watch
Which receipts actually qualify. Eligibility is not automatic and the liquidity and representativeness thresholds do real work in the Ibovespa methodology.
And what index-tracking money does about it. Passive funds benchmarked to the Ibovespa will have to buy whatever enters, which makes the first inclusion window in 2027 a mechanical flow event as much as a methodological one.
What a BDR Is
A Brazilian Depositary Receipt is a certificate traded on the B3 that represents shares held by a custodian in another market. The holder gets economic exposure to the foreign share without owning it directly and without needing an offshore account.
The instrument exists because Brazilian capital controls and custody rules historically made direct foreign holdings awkward for retail investors and impossible for many domestic funds. A receipt solves the plumbing problem.
The category that matters here is narrower than the general BDR market. This rule change concerns receipts issued by Brazilian companies whose primary listing sits abroad, not receipts over Apple or Nvidia.
The Companies This Was Written For
A meaningful group of Brazilian businesses now lists in New York rather than São Paulo. StoneCo, PagSeguro, XP, Nu Holdings and Vinci Partners all built their businesses almost entirely in Brazil and chose United States listings for valuation, liquidity and governance reasons.
From the index’s point of view they simply disappeared. A benchmark meant to represent the Brazilian equity market excluded some of the largest Brazilian companies created in the past decade, purely on the basis of where the primary listing sat.
That is a measurement problem rather than a policy one, and it gets worse as the trend continues. Each new offshore listing makes the Ibovespa a slightly less accurate description of Brazilian corporate value.
Whether individual names actually qualify under the new rule depends on their BDR liquidity on the B3, which for several of them is thin. Eligibility is not the same as inclusion.
The Cap Is the Compromise
Ten percent is not an arbitrary number. It is large enough to admit the category meaningfully and small enough that the index cannot become a proxy for a handful of Nasdaq listings.
It also caps the mechanical flow. Passive money tracking the Ibovespa will have to buy whatever is included at whatever weight the methodology assigns, and a category ceiling puts a bound on how much of that flow leaves the domestic market for receipts.
The unresolved question is what happens if BDR-eligible companies keep growing. A cap that binds is a cap that distorts, and at that point B3 will face the same choice again with less room to compromise.
More: Brazil news in English, every day from The Rio Times.
Frequently Asked Questions
What did B3 announce?
That Brazilian depositary receipts will become eligible for the Ibovespa from the first half of 2027, capped at 10 percent of the index.
What is the rule today?
BDRs are not eligible for Ibovespa inclusion at all.
Is the 10 percent per issuer?
No. It is a cap on the combined weight of all BDRs in the theoretical portfolio.
Do the usual criteria still apply?
Yes. Liquidity and representativeness thresholds still have to be met.
When was it announced?
8 September 2026.
Sources: InfoMoney, B3.
This article was drafted with automated assistance and reviewed before publication. How we use AI · Report an error
Read More from The Rio Times