Brazil’s Central Bank Seeks to Encourage Greater Competitiveness Among Banks
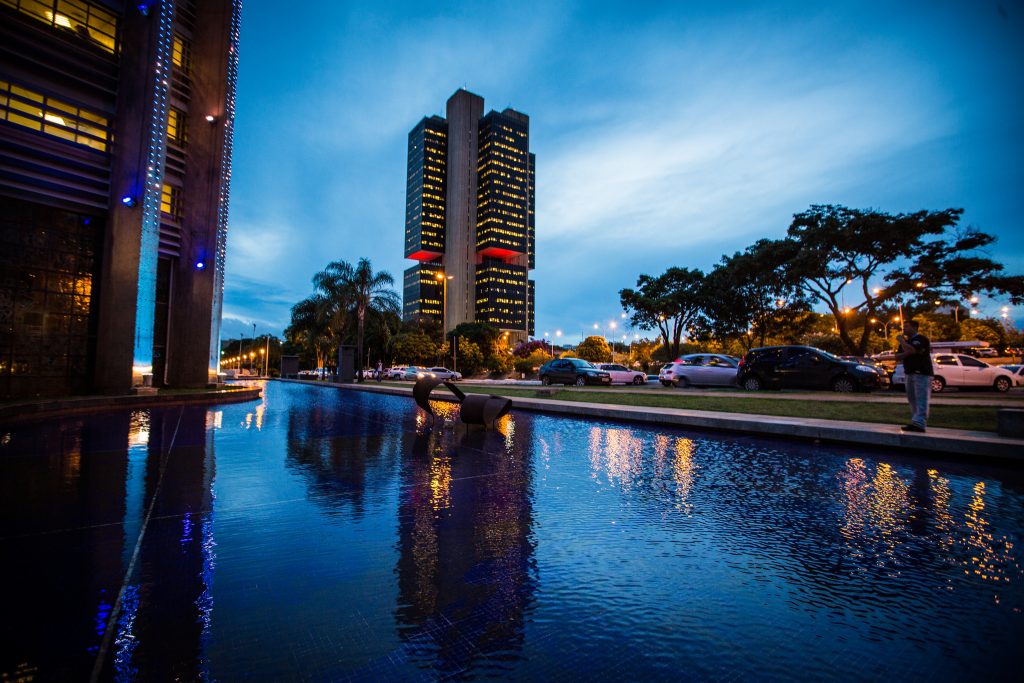
RIO DE JANEIRO, BRAZIL – The Central Bank (BC) seeks to encourage banking competitiveness in the country in order to reduce interest charges and expand the population’s access to financial services.
The president of the institution, Roberto Campos Neto, said on Thursday, January 9th, that technological advances in the sector, such as open banking and the instant payment system, will open the market and will be “a milestone in the Brazilian financial industry”.

“Much of what we are doing is to match digital networks with physical networks. All the barriers that keep the digital platform from competing are in this area that we are acting,” said Campos Neto when introducing the results of the implementation of the BC# Agenda. Launched in May 2029, it includes the strategic actions of BC for the coming years.
The institution expects that the major banks will also succeed in this new environment of greater structural competition. “Our goal is to create banking competition. Looking ahead, what will financial intermediation look like in the future? The growth of technology is inherent and we need to unlock the barriers to competition,” said Campos Neto.
In the context of open banking, the banking data belong to the customers and the financial institutions will share this information, products, and services through the opening and integration of technology platforms and infrastructures. The public consultation on this new system has already begun and the implementation process is expected to be finalized later this year.
In the case of the instant payment system, also scheduled for the end of this year, the goal is to allow transactions at any time and make them cheaper.
The BC# Agenda comprises four pillars: inclusion, competitiveness, transparency, and education.
On competitiveness, BC launched Lift Learning this year, a program to encourage the development of innovative banking solutions, and created the area of competition and structure within the bank, which works on projects to modernize the infrastructure of the financial market.
Overdraft was also redesigned, with lower interest rates, less aggressiveness, and greater rationality; the proposal for the use of bank slips for deposits and the consultation for the regulation of ATMs in this new scenario of digital banks.
New click
For Campos Neto, all these measures to foster competitiveness, and the other items on the BC# Agenda, are part of a cycle to reinventing the market with private resources. The aim is to encourage lower long-term interest rates to allow private financing for large agents and, consequently, to allow more public promotion, with less credit cost, to small and medium-sized enterprises, ensuring greater inclusion and social participation in the financial system.
In addition to the drop in interest rates, cooperatives, micro-credit incentives, and the new rural credit policy are part of the Central Bank’s agenda. According to the bank, 275 actions were developed in the first stage of BC#, the majority still in progress. The second stage will be announced in June this year.
Financial education
According to Campos Neto, part of the problem of access to credit and high default in the country is the lack of financial education by the population. “We want to encourage savings and provide people with a greater understanding of financial products,” said Campos Neto about the fourth pillar of the BC# Agenda.
The institution has already encouraged the renegotiation of debts by banks and, in return, debtors participate in financial education courses. And one of the BC’s projects is that these courses result in certification and benefits for the citizen in the banking system. According to the bank, the Brazilian Federation of Banks (FEBRABAN) is developing this electronic financial education platform.
According to the Central Bank, two renegotiation efforts are planned for 2020, looking to serve at least one million clients in each.
More: Brazil news in English, every day from The Rio Times.
This article was produced by The Rio Times’ automated AI newsroom. Editorial responsibility: Matthias Camenzind, Publisher and Editor-in-Chief. The Rio Times also runs Ask Rio Times, which answers from 100,000+ of our own articles, the daily Latin America Power Map, and prediction-market odds on elections and markets.. How we use AI · Report an error
Brazil runoff, Sunday, October 25: When is the Brazil runoff election. Latest: Brazil runoff polls, Flávio 51%, Lula 49%.