Brazil Stocks Rise 1.4% While the Real Stays Weak | Morning Call, Nov 9
Key Facts
- The real is the story going into the open with the US dollar at its highest close since 29 December 2025 after rising 10.41% over 20 sessions
- The central bank’s Copom minutes land tomorrow at 8:00 BRT and will explain the reasoning behind the 4 November rate decision that traders are still digesting
- The weekly Focus survey at 8:30 BRT is today’s main Brazilian data point after the last reading put the 2027 inflation forecast at 4.76%
- Lula’s first national address since his re-election promised fiscal responsibility but gave no detail on spending cuts, which is what investors want to see
- CSN’s talks to sell its cement arm to China’s Huaxin put CSNA3 in focus as a R$12.7bn deal under exclusive negotiation that would still need approval from the antitrust regulator Cade
Today’s Focus
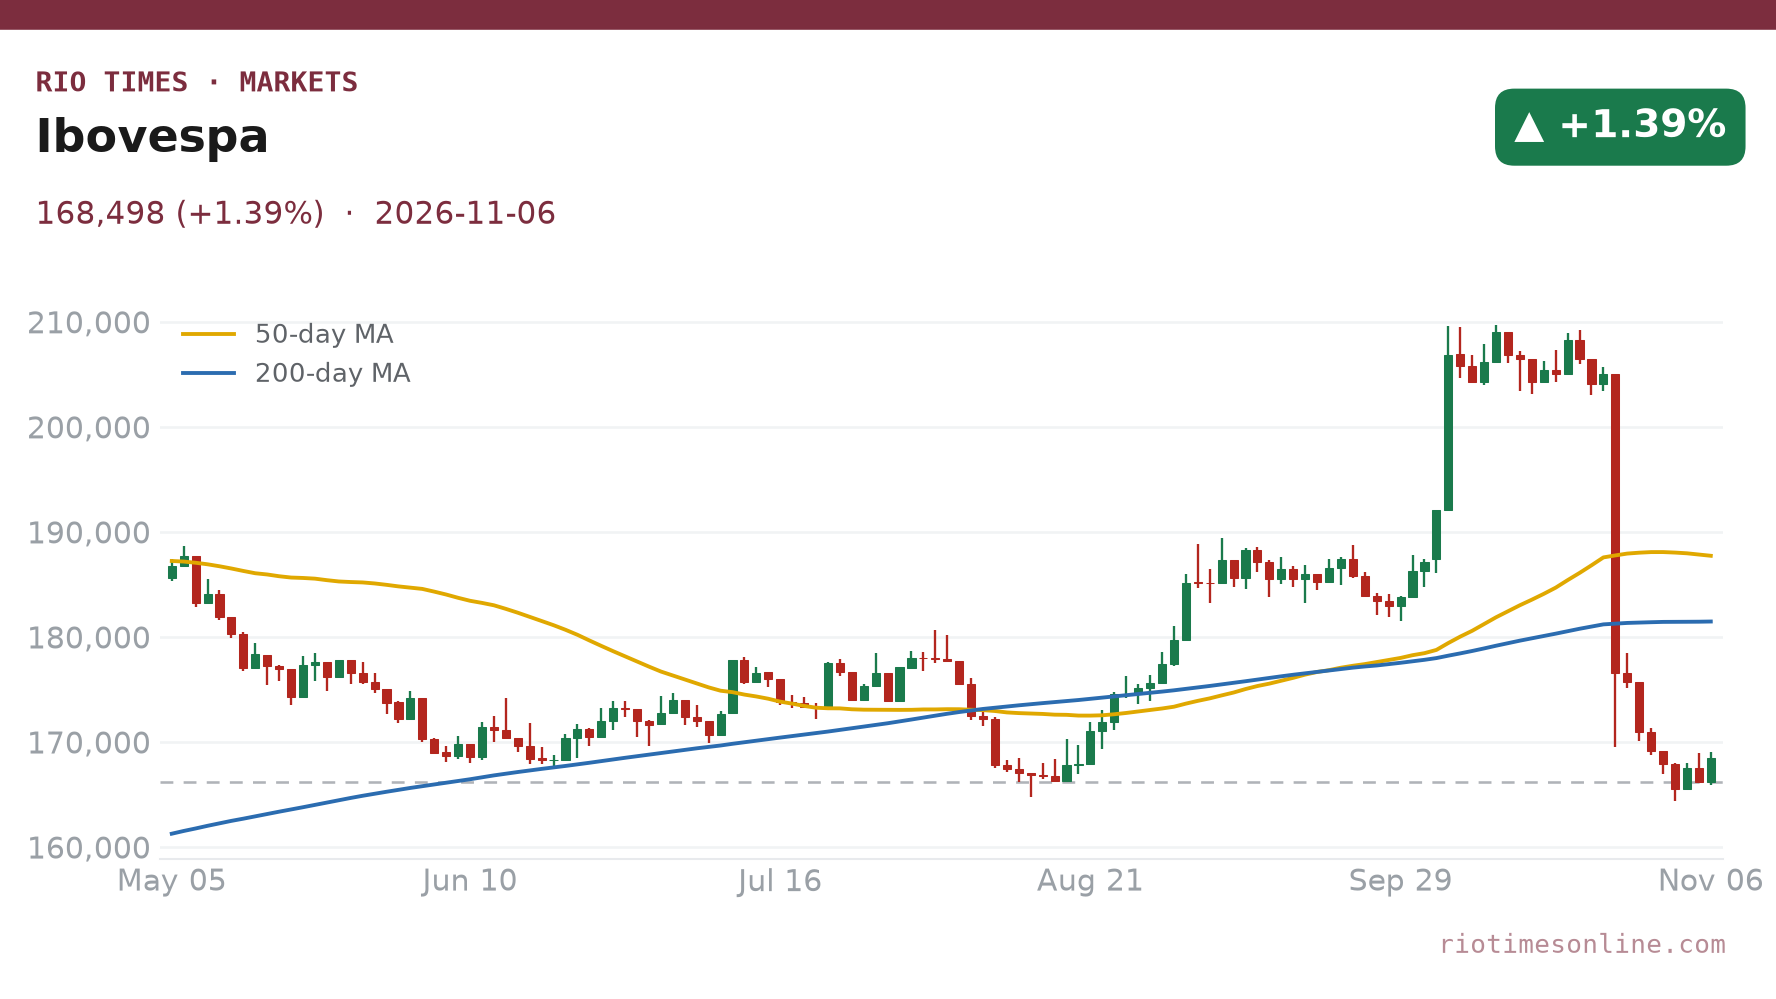
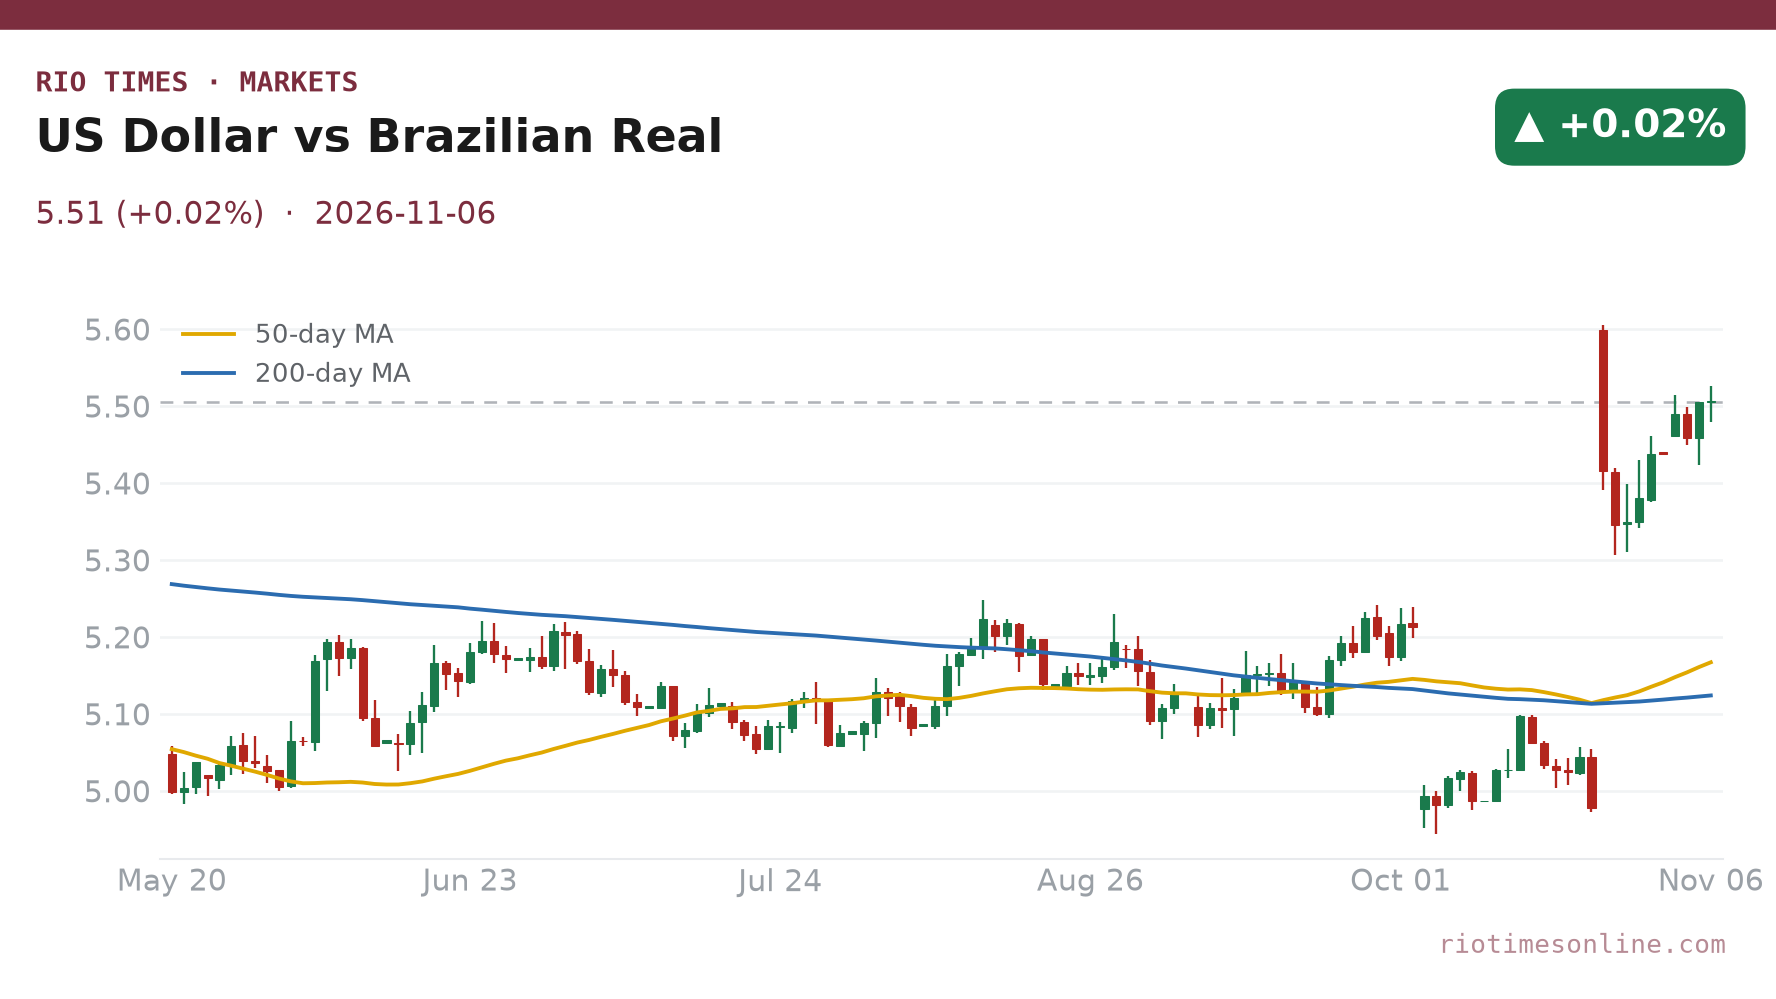
Brazil’s currency is the first thing to watch before the bell. The dollar closed Friday at its highest level since 29 December 2025, up 10.41% over 20 sessions, and the Ibovespa, Brazil’s main stock index, sits 19.4% below its 9 October peak.
Two Brazilian events frame the day. The Focus survey, the central bank’s weekly poll of economists, arrives at 8:30 BRT (Brasília time), and the minutes of the Copom, the committee that sets the Selic benchmark interest rate, follow tomorrow at 8:00 BRT.
The politics matter as much as the numbers. President Lula used his first national address since re-election to reaffirm his commitment to fiscal responsibility without naming specific measures.
We could not confirm early futures indications for the open, so treat direction as open. The tone from Friday’s Wall Street session was firm, but a stronger global dollar argues against a quiet day for the real.
What matters today. Watch whether the Focus survey keeps pushing up inflation and Selic forecasts, because that sets how much the Copom minutes can reassure a nervous real.
Today’s Economic Events
| Instrument | Level | Session |
|---|---|---|
| Ibovespa (Brazil) | 168,498 | +1.39% |
| S&P 500 (US) | 7,377 | +0.31% |
| USD/BRL | 5.5064 | +0.02% |
Source: market close, 6 November 2026.
01 The setup in one read
Brazil starts the week with a weak currency and a long list of questions. The dollar’s 10.41% rise in 20 sessions has put the real at its weakest close since 29 December 2025, while the Ibovespa is 17.52% lower than 20 sessions ago.
Friday gave one subordinate relief: the Ibovespa rose 1.39% on the day. That is a bounce inside a deeper slide, not a change of direction.
Today’s catalysts are domestic. The Focus survey comes first, then car industry data, and then tomorrow’s Copom minutes and US inflation figures at 10:30 BRT.
Foreign investors should remember that Brazil’s rates are among the highest in the large economies. A small shift in the expected path of the Selic therefore moves bonds, the real and bank and retail shares together.
The evidence points to two domestic causes layered on a global one: a stronger world dollar, rising inflation forecasts that push back hopes of lower interest rates, and a government that has promised discipline without detail. We lack today’s futures prices, so the ranking rests on the Focus trend and Friday’s cross-asset moves rather than on live indications.
The variable to watch is the Focus forecast for the Selic at the end of 2027, which was 12.50% last week.
02 Where Brazil is set to open
| Instrument | Last close | Indicated | Watch today |
|---|---|---|---|
| Ibovespa | 168,498 (Friday, +1.39%) | — (futures not confirmed); Wall Street tone was firm | 170,000 as resistance, 160,000 as support |
| USD/BRL | 5.5064 | — (not confirmed); stronger global dollar argues for firmness | 5.50 round number; 5.59 is the 12-month high |
| Selic (benchmark rate) | 13.75% (held on 4 November) | — (no live pricing found) | Focus survey 8:30 BRT; Copom minutes tomorrow |
| US 10-year Treasury yield | 4.867% | — | Higher US yields pull money away from emerging markets |
We could not verify early futures indications, so the table shows context and levels rather than a forecast. The board below sets out Friday’s full closing figures.
The global backdrop is mixed. The dollar index rose 0.74% on Friday and the US 10-year yield stands at 4.867%, which weigh on emerging markets, while the S&P 500 rose 0.31% and the VIX fear gauge fell 9.01%.
Our own price history offers a sober note on the real. In 18 earlier cases since 2007 when the dollar rose this much in 20 sessions, it was higher 20 sessions later in only 6 (33%), with a median move of -1.3% and a worst case of -11.4%.
History is not a forecast, and the best case in that sample was a further +29.5%. The point is that sharp currency runs often partly reverse, but not reliably. Rio Times · Live Market Intelligence
Live Market IntelligenceBrazil Morning Call — Live Board
Brazil Morning Call — Live Board
Instrument Last Change YoY Prev. High Low Volume
IBOV
168,498.45
+1.39%
+9.89%
166,191.45
—
—
—
USD/BRL
5.51
-0.03%
+3.27%
5.51
5.51
5.50
—
EUR/BRL
6.14
+0.21%
-0.33%
6.13
6.14
6.13
—
SELIC
13.75%
—
—
—
—
—
BRENT
97.04
-1.30%
+51.48%
98.32
98.42
96.78
2,774
WTI
90.16
-0.74%
+49.94%
90.83
91.42
89.80
22,572
IRON ORE
161.91
—
+55.73%
161.91
161.91
1
GOLD
4,131
+1.38%
+0.23%
4,075
4,143
4,063
37,015
SILVER
52.92
+2.16%
+5.47%
51.80
53.47
51.42
10,786
LITHIUM
60.91
+1.21%
+0.03%
60.18
61.25
60.27
204,575
SOY
1,198
+0.76%
+7.35%
1,189
1,203
1,193
14,683
CORN
441.75
+0.06%
+2.79%
441.50
443.50
440.50
22,107
WHEAT
590.25
-0.17%
+10.17%
591.25
594.00
588.00
11,996
COFFEE
280.15
+1.08%
-32.45%
277.15
282.50
276.00
24,446
SUGAR
18.25
-1.67%
+28.52%
18.56
18.60
18.13
83,842
ORANGE JUICE
130.55
+1.63%
-28.15%
128.45
140.35
135.75
440
COTTON
78.54
-0.22%
+22.13%
78.71
78.38
77.73
15,128
BEEF
214.05
-0.16%
-6.34%
214.40
214.60
210.85
34,881
CATTLE
318.38
-2.05%
-5.15%
325.05
320.35
312.05
14,677
COCOA
5,119
-1.20%
-16.11%
5,181
5,400
5,192
26,530
PETR4
45.36
+0.00%
+46.28%
45.36
45.36
—
—
VALE3
64.04
+0.00%
-2.23%
64.04
64.04
—
—
SUZB3
53.40
+2.12%
+9.76%
52.29
53.42
50.10
13,908,400
KLABIN
17.60
+0.00%
-3.29%
17.60
17.60
—
—
SLCE3
16.61
+1.59%
+15.99%
16.35
16.70
16.25
1,312,900
ABEV3
15.48
+0.00%
+18.35%
15.48
15.48
—
—
ITUB4
40.53
+0.00%
+4.03%
40.53
40.53
—
—
BBDC4
14.20
+0.00%
-24.10%
14.20
14.20
—
—
BBAS3
17.13
+0.00%
-25.07%
17.13
17.13
—
—
B3SA3
14.39
+0.00%
+9.85%
14.39
14.39
—
—
WEGE3
48.19
+0.00%
+9.75%
48.19
48.19
—
—
PRIO3
60.48
+0.00%
+57.25%
60.48
60.48
—
—
RENT3
30.29
+0.00%
-26.39%
30.29
30.29
—
—
AZZA3
14.76
+4.98%
-47.66%
14.06
15.19
13.80
4,143,600
CSNA3
4.41
+0.00%
-48.12%
4.41
4.41
—
—
GGBR4
24.15
+0.00%
+26.31%
24.15
24.15
—
—
ENEV3
26.84
+0.00%
+40.16%
26.84
26.84
—
—
LREN3
9.93
+4.20%
-31.80%
9.53
10.20
8.95
67,961,100
03 On the B3 radar today — the Focus survey and car data frame a quiet calendar
| Item | When | Why it matters |
|---|---|---|
| BCB Focus survey | 8:30 BRT | Economists’ forecasts for inflation and the Selic; last week’s reading put the 2027 inflation forecast at 4.76% |
| IGP-DI inflation (price index) | 8:00 BRT | Previous reading 1.5; no consensus forecast published |
| Mexico inflation, headline and core | 9:00 BRT | Consensus 3.65% annual headline (previous 3.45%); core 3.76% (previous 3.75%), a read on Latin American rate paths |
| New car sales and auto production | 11:00 BRT | Car sales consensus -0.8 (previous 2.3); production 1.8 (previous -1.1) |
| Chile trade balance | 8:30 BRT | Consensus 2,090 (previous 2,047); Chile’s copper-linked trade is a gauge for the region |
| Colombia inflation | Evening | Consensus 6.4% annual (previous 6.29%) |
| Corporate earnings and ex-dividends | — | None confirmed for today |
| Copom minutes (tomorrow) | 8:00 BRT Tuesday | Detail on the 4 November decision and the committee’s guidance |
Today’s calendar is light, which hands more weight to the Focus survey. If forecasts for the Selic at the end of 2027 climb again from 12.50%, expect pressure on the real and on rate-sensitive shares.
We found no verified earnings or ex-dividend dates for today, so we have not listed any. The car industry data is a modest read on consumer credit, which high interest rates squeeze.
04 Copom and the macro backdrop
The Copom kept the Selic at 13.75% on 4 November. The committee voted unanimously, so the minutes due tomorrow at 8:00 BRT, published at bcb.gov.br, are the first full account to read.
Before the meeting, the prediction market Polymarket priced no change at 85.5% and a 0.25-point cut at 12.5%. For the next meeting, in December, it priced no change at 74.5% and a cut at 23.5%; we found no odds for an August meeting.
Last week’s Focus survey put the 2026 inflation forecast at 5.22% and the 2027 forecast at 4.76%. The official target is 3%, and the latest 12-month inflation reading, to September, was 4.58%.
Economists now expect the Selic at 13.50% at the end of 2026 and 12.50% at the end of 2027. Higher-for-longer rates support the real in theory, but only if investors trust the fiscal picture, and Lula’s address did not settle that.
Friday’s US jobs report was the session’s main data point. US Non Farm Payrolls rose by 165,000 against a forecast of 65,000 and a previous 60,000, and US Nonfarm Payrolls Private rose by 159,000 (forecast 64,000). Manufacturing payrolls added 19,000 (forecast 5,000) and government payrolls added 6,000 (forecast -5,000).
The US unemployment rate was 4.1% against a forecast of 4.2%. The U-6 rate, which also counts part-time workers who want full-time jobs, was 7.9% against a forecast of 7.6%.
The University of Michigan consumer survey showed lower inflation worries. Michigan 1 Year Inflation Expectations were 4.3% (forecast 4.7%) and Michigan 5 Year Inflation Expectations were 3.4% (forecast 3.6%).
Brazil’s Balance of Trade showed a surplus of US$9.32 billion in October against a forecast of US$9 billion and US$7.27 billion in September. A larger surplus brings more dollars into the country, which helps the real. Source: RT economic calendar (RT).
05 Corporate stories to watch today
CSN, the steel and mining group, has agreed a 10-day exclusivity period to negotiate the sale of CSN Cimentos, its cement arm, to China’s Huaxin in a deal valued at R$12.7bn including debt. No final contract is signed yet, and a sale would still need approval from Cade, Brazil’s antitrust regulator.
CSNA3 closed up 8.9% on Friday on R$120m of turnover, so today tests whether a final deal extends that move. A deal of this size helps CSN reduce debt, the usual worry with the stock.
Ueno Bank is a separate story: Paraguay’s central bank ordered the liquidation of the lender on 3 November. It is a small-lender case, but it reminds investors that confidence in smaller banks can crack quickly.
Petrobras (PETR4) led Friday’s turnover at R$2,135m and PRIO3, an oil producer, fell 1.7% on R$757m. The oil fund USO fell 12.10% over five sessions, so oil names carry the largest commodity risk today.
06 The levels to watch at the open
For the Ibovespa, the nearest resistance is the round 170,000, just above Friday’s close of 168,498. The 12-month high of 209,067 on 9 October is far away, and Friday’s close is 8.9% above the 12-month closing low of 154,770 on 21 November 2025.
For the dollar against the real, 5.50 is the round number that Friday’s 5.5064 sits on. The next ceiling is the 12-month closing high of 5.59 set on 22 December 2025, which is 1.5% above Friday’s close.
A break above 5.59 would mark a new phase of real weakness, while a slide below 5.50 would suggest the recent run is cooling. The minutes and the US inflation figures tomorrow are the next dated tests.
Latin America feels this directly: Mexico and Colombia publish inflation today, and Brazil’s real moves usually pull the region’s currencies. Chilean, Mexican and Colombian investors in Brazilian shares carry the same dollar risk as Brazilian importers.
07 What to watch
- Focus survey: 8:30 BRT today: do 2027 inflation and Selic forecasts keep rising?
- Copom minutes: 8:00 BRT Tuesday: guidance on the next steps after the 4 November decision
- US inflation: 10:30 BRT Tuesday: consensus 3.7% annual rate, a driver of the global dollar
- Brazil October inflation: 9:00 BRT Thursday 12 November: the IPCA consumer-price index from IBGE, the statistics agency, against the 3% target
Background: Trinidad Bank Group Reports US$340M, Up 5.8%.
Background: Dangote Falls Short of 10 Million Investors.
More: Brazil news in English, every day from The Rio Times.
Frequently Asked Questions
What are the Copom minutes?
They are the central bank’s detailed written account of its rate meeting, published a few days later. Traders read them for clues about the next move in the Selic.
What is the Focus survey?
It is a weekly poll of economists run by Brazil’s central bank on inflation, growth, the Selic and the exchange rate. Markets treat it as a gauge of expectations.
Why does the real matter for stocks?
A weaker real raises the cost of imports and foreign debt, and it cuts the dollar value of Brazilian shares for foreign investors. It also tends to move with fiscal worries.
What are the odds of a Selic cut?
Before the 4 November meeting, Polymarket priced a December cut at 23.5% and no change at 74.5%. We found no odds for August, and prices may have moved since.
Market data: The Rio Times
This article was produced by The Rio Times’ automated AI newsroom. Editorial responsibility: Matthias Camenzind, Publisher and Editor-in-Chief. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.
Brazil runoff, Sunday, October 25: When is the Brazil runoff election. Latest: Brazil runoff polls, Flávio 51%, Lula 49%.