Fed Hike Bets Lift Dollar After Strong US Jobs Data | Global Economy, Nov 9
Key Facts
- The prediction market Polymarket puts about a 77% chance on a Fed rate hike at the 8–9 December meeting after US employers added 165,000 jobs in October against a forecast of about 65,000.
- The Nasdaq, the tech-heavy US share index, is still down 10.2% over 20 sessions, and sits 10.9% below its 6 October high of 27,600 even after Friday’s bounce.
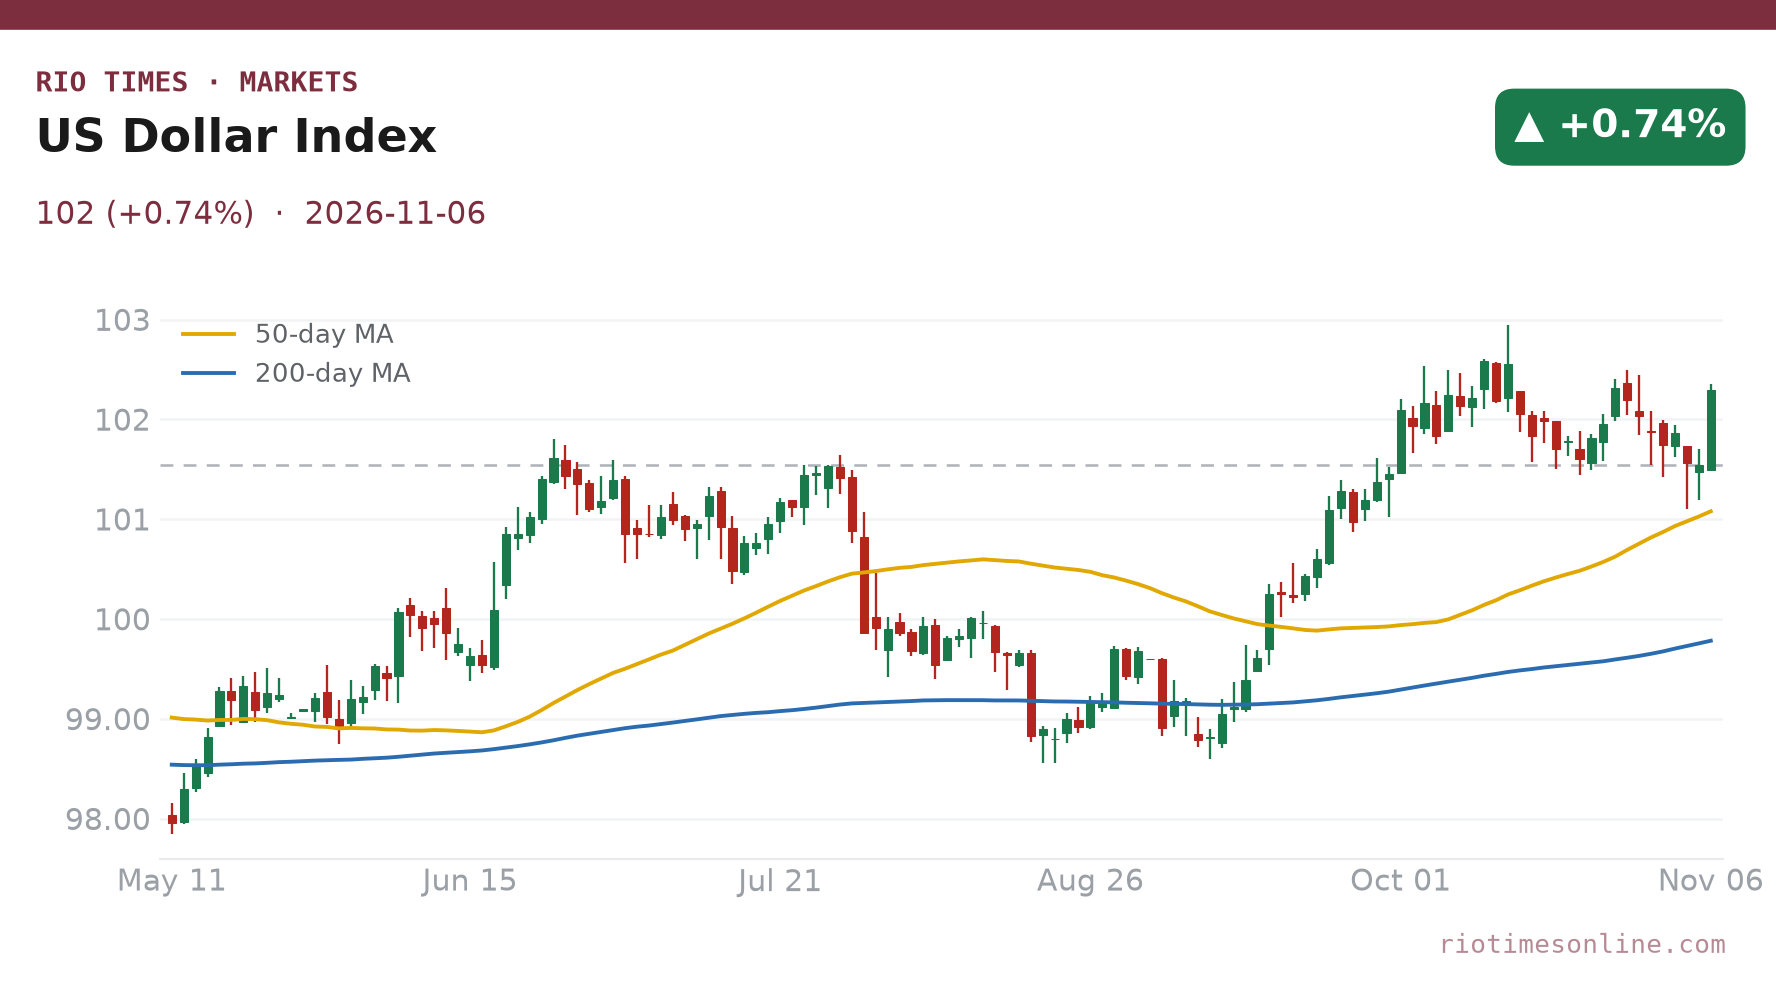
- The dollar is the clear winner of the week’s rate repricing, with the dollar index, which measures the US currency against a basket of rivals, at 102.298 after rising 0.74% on Friday.
- Oil has fallen hard in a week, with the main US oil fund down 12.10% over five sessions on talk of an end to the war involving Iran.
- Fear is easing but has not gone, as the VIX, Wall Street’s gauge of expected share-price swings, closed at 25.64 after falling 9.01% on Friday, yet it is 32.03% above its level five sessions earlier.
Today’s Focus
The Federal Reserve, America’s central bank, was supposed to be finished with raising interest rates. Friday’s jobs report has put another increase back on the calendar for 8–9 December.
US employers added 165,000 jobs in October when economists expected about 65,000. Unemployment was 4.1%, and pay per hour rose 0.4% on the month.
That is bad news for anyone hoping for cheaper money. Strong hiring gives the Fed room to keep tightening while prices are still pushed up by the conflict involving Iran.
Yet shares rallied on Friday and oil kept falling, so the market is torn between relief that the war may end and worry that the Fed will not ease up. The next test is US inflation data on Tuesday.
What matters today. A Fed that is still raising rates keeps the dollar firm and borrowing costs high, and that squeezes every emerging market, Latin America included.
| Instrument | Level | Session |
|---|---|---|
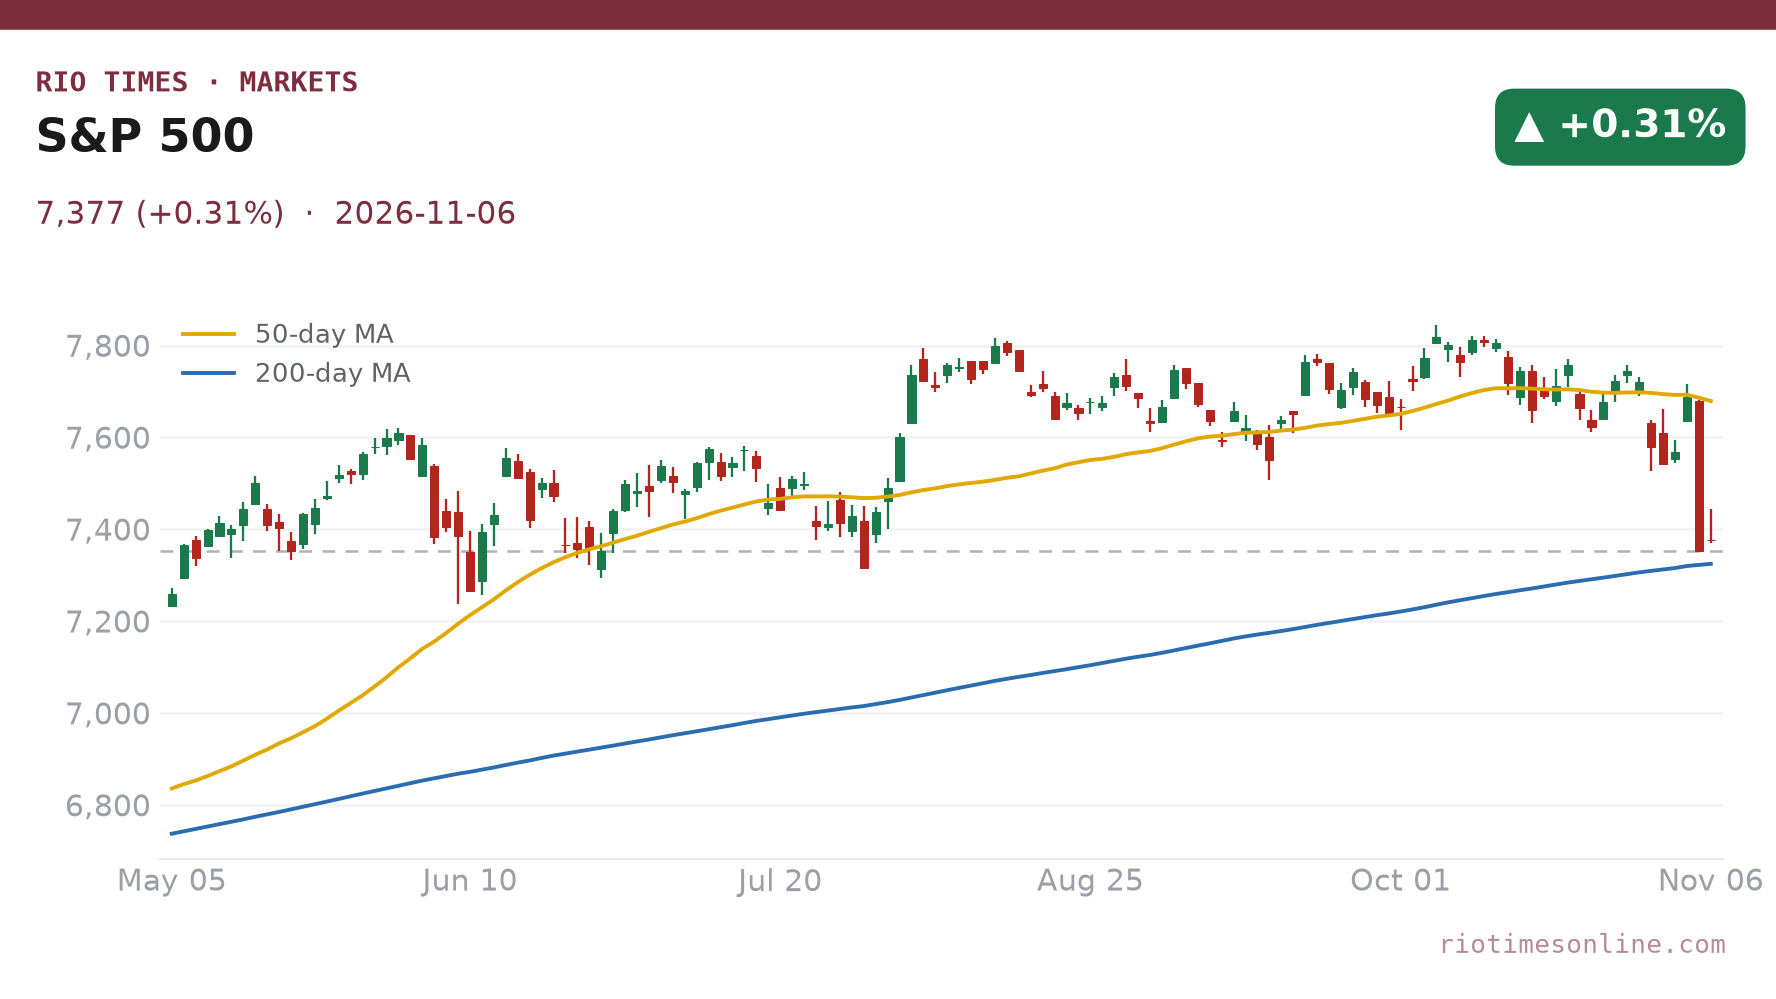
| S&P 500 (US) | 7,377 | +0.31% |
| Ibovespa (Brazil) | 168,498 | +1.39% |
| USD/BRL | 5.5064 | +0.02% |
Source: market close, 6 November 2026.
01 The world in one read
Markets shut on Friday with a puzzle. The Fed looks more likely to raise interest rates again, yet shares rose and oil kept sliding.
The answer is that two forces are pulling in opposite directions. A strong US jobs report says the economy can take higher rates, while talk of an end to the war involving Iran is draining the oil price that fuelled inflation.
Over the past 20 sessions, the Nasdaq has fallen 10.2% and the S&P 500, the broad index of 500 large US companies, has fallen 5.6%. The S&P 500 is 5.7% below its 6 October peak of 7,819 and 16.3% above its 12-month low of 6,344.
That makes this a pullback inside a long climb rather than a collapse, but a sharp one. Markets are closed at weekends, so Monday’s first prices will be the first test of how the world reads Friday’s data.
The evidence points one way on policy: a big jobs beat, unemployment at 4.1% and firm pay growth leave little reason for the Fed to pause in December. The dollar and the 10-year Treasury yield moved the way that story predicts.
Shares and oil tell a different story, one of relief that the war may wind down, and the two pictures can both be true for a while. Confidence is medium because market odds of a hike can swing sharply on one data release; the variable to watch is Tuesday’s US inflation reading.
02 The global board
| Instrument | Level | Change | Read |
|---|---|---|---|
| US 10-year Treasury yield | 4.867% | +0.58% | The interest rate the US government pays to borrow for a decade; it rose as hike bets firmed |
| Dollar index (DXY) | 102.298 | +0.74% | The biggest mover of the day; hike bets pull money into the dollar |
| S&P 500 | 7,377 | +0.31% | Held up despite higher yields on post-election relief |
| Nasdaq | 24,579 | +1.09% | Tech led the bounce but remains deep below its peak |
| Dow Jones | 51,286 | −0.46% | The 30-company index lagged; the rally was narrow |
| VIX fear gauge | 25.64 | −9.01% | Calmer, but still elevated |
| Gold | $4,066/oz | −0.49% | Eased on the day after a strong week for the metal |
| Silver | $51.9/oz | +0.34% | Edged higher |
Read across the board and the message is rate worry meeting equity relief. Yields and the dollar rose together, the classic reaction to a Fed that may tighten further.
Shares ignored it for a day, with the Dow slipping while the Nasdaq jumped. A rally led by a few big technology names is less secure than one that carries the whole market. Rio Times · Live Market Intelligence
Live Market IntelligenceGlobal Markets — Live Board
Global Markets — Live Board
Instrument Last Change YoY Prev. High Low Volume
SPX
7,377
+0.31%
—
—
—
—
—
NDX
26,990
+1.35%
—
—
—
—
—
DJI
51,286
-0.46%
—
—
—
—
—
RUT
2,754
+0.89%
—
—
—
—
—
US10Y
4.8590
+0.45%
—
—
—
—
—
VIX
24.33
-5.11%
—
—
—
—
—
DAX
25,977
+0.61%
—
—
—
—
—
FTSE
10,733
+0.56%
—
—
—
—
—
CAC
8,157
+0.22%
—
—
—
—
—
STOXX
652.15
+0.59%
—
—
—
—
—
NIKKEI
58,776
+2.33%
—
—
—
—
—
HSI
24,449
-0.13%
—
—
—
—
—
KOSPI
5,019
-0.81%
—
—
—
—
—
CSI300
4,056
+0.05%
—
—
—
—
—
NIFTY
25,045
+0.23%
—
—
—
—
—
TSX
35,789
+0.52%
—
—
—
—
—
GOLD
4,102
+0.67%
-0.48%
4,075
4,143
4,063
54,670
SILVER
52.46
+1.26%
+4.54%
51.80
53.47
51.42
15,199
03 The main event — a jobs report that keeps the Fed hiking
The October jobs figure of 165,000 was about two and a half times what economists forecast, at about 65,000. Revisions to the prior two months added another 84,000 jobs.
Futures markets reacted at once. On Polymarket, a prediction market where traders bet real money, the chance of a quarter-point hike in December stood at 76.5% at 11:08 p.m. ET on Sunday 8 November.
Why we show this: prediction markets turn real-money bets into a live probability that moves within minutes of the news, which is why investors, campaigns and newsrooms in the United States now follow them closely. We show them next to polls and official results, never instead of them.
Higher-for-longer rates matter for mortgages, company debt and emerging-market currencies. The detail of the jobs report was also strong. US Non Farm Payrolls, the headline figure, rose by 165,000 against a forecast of 65,000, and US Nonfarm Payrolls Private rose by 159,000 (forecast 64,000), according to the US Bureau of Labor Statistics, the official data agency. Manufacturing payrolls added 19,000 (forecast 5,000).
The U-6 Unemployment Rate, which also counts part-time workers who want full-time jobs, was 7.9% against a forecast of 7.6%. The University of Michigan consumer survey showed calmer prices ahead: Michigan 1 Year Inflation Expectations were 4.3% (forecast 4.7%) and Michigan 5 Year Inflation Expectations were 3.4% (forecast 3.6%).
Europe was weaker. Euro area retail sales fell 0.7% on the month against a forecast fall of 0.1% and a 0.4% rise before, according to the EU statistics office Eurostat. Brazil’s Balance of Trade showed a surplus of US$9.32 billion in October against a forecast of US$9 billion. Source: RT economic calendar (RT).
04 Policy and data
The Fed’s target range stands at 3.75%–4.00%. It held on 28 October by a 10–2 vote, with two members, Governor Lisa Cook and Cleveland Fed President Beth Hammack, preferring a quarter-point increase.
Tuesday is the next big test: US consumer prices are due, with the annual rate forecast at 3.7%, unchanged, and the core rate, which strips out food and energy, at 2.5% against 2.6% before. Monthly forecasts are 0.3% for the headline after 0.6%, and 0.2% for core after 0.3%.
Four Federal Reserve officials, Christopher Waller, Lorie Logan, Michelle Bowman and Jeffrey Schmid, speak on Tuesday, and the US Treasury sells 10-year notes in an auction. A weak auction would push yields higher and add to the pressure on shares.
In Asia, China’s foreign-exchange reserves for October came in at 3.405 against a forecast of 3.4, a small beat that shows no sign of stress. China’s trade figures arrive on Tuesday, alongside Japan’s Reuters Tankan sentiment survey and a 30-year Japanese government bond auction.
05 Commodities and currencies
Oil is where the war story shows up most clearly. The main US oil fund is down 12.10% over five sessions, though it edged up 0.13% on Friday.
Official US data from the Energy Information Administration, at eia.gov, show commercial crude stocks of 409.8 million barrels for the week ending 30 October, down 0.9 million. Gasoline stocks fell 0.2 million to 209.0 million barrels, and distillate stocks, which include diesel and heating oil, fell 3.6 million to 99.3 million.
Gold at $4,066 an ounce eased 0.49% on Friday, but the main gold fund is up 4.7% over five sessions. Buyers are using it as insurance against war and market swings, even as higher rates usually weigh on it.
The dollar index at 102.298 is the one clean signal. Strong US jobs and a hawkish Fed give investors a reason to hold dollars, which makes everything priced in dollars dearer for the rest of the world.
06 The Latin American read-through
For Latin America, the message is mixed. A firm dollar and high US yields tighten conditions, while cheaper oil helps importers and hurts producers.
The board shows Brazil’s Ibovespa, its main stock index, closed at 168,498, up 1.39% on Friday and in step with Wall Street. It remains 19.4% below its 9 October high of 209,067 and has fallen 17.52% over 20 sessions, so the bounce is small against the damage.
The real, Brazil’s currency, was little changed at 5.5064 per dollar, up 0.02%. Oil-linked names felt the crude slide: PRIO3, the oil producer Prio, fell 1.7% on R$757m of turnover, and UGPA3, the fuel distributor Ultrapar, fell 2.7% on R$399m.
Mexico’s peso strengthened to 18.6285 per dollar, down 0.68% for the dollar, and the IPC, Mexico’s main index, closed at 71,394, 0.3% below its 52-week high. Chile’s peso firmed to 976.64 per dollar.
Brazil’s central bank publishes the minutes of its latest Copom meeting on Tuesday; Copom sets the Selic, the benchmark interest rate. Mexico’s inflation data are due Monday, with the annual rate forecast at 3.65% against 3.45% before, and Colombia’s follow late in the day.
07 What to watch
- US inflation on Tuesday: The annual rate is forecast at 3.7% and core at 2.5%; a hotter reading would lift the December hike odds above the current 77%.
- Fed speakers and Treasury auction: Waller, Logan, Bowman and Schmid speak Tuesday, followed by a 10-year note auction; the tone of both shapes yields.
- The 8–9 December Fed meeting: Whether the central bank delivers the quarter-point hike markets expect, and what it signals for the path of rates.
- Index levels to hold: The S&P 500 has support at its 12-month low of 6,344 and resistance at its 7,819 peak; the Nasdaq between 20,795 and 27,600.
Background: US Adds 165,000 Jobs as Dollar and Yields Rise.
Background: Wall Street Plunges 4.4% as Fear Gauge Jumps.
Frequently Asked Questions
Will the Fed raise interest rates in December?
The prediction market Polymarket puts the chance of a quarter-point rise at the 8–9 December meeting at about 77%, as of 11:08 p.m. ET on Sunday 8 November. Tuesday’s US inflation data could move that figure.
Why did US stocks rise after a strong jobs report?
Investors took comfort from post-election relief and talk of an end to the war involving Iran, which pushed oil lower. The rally was narrow, with the Dow falling while the Nasdaq rose.
What does a strong dollar mean for Latin America?
It makes dollar debts costlier to repay and tends to weaken local currencies. Brazil’s real was little changed on Friday, and Mexico’s peso strengthened.
Is the stock market fall a sign of a crash?
The Nasdaq is 10.9% below its 6 October high of 27,600 and the S&P 500 is 5.7% below its peak of 7,819, a sharp pullback rather than a collapse. History since 2007 shows markets higher 20 sessions later in 57% of comparable S&P 500 cases, but that is not a forecast.
Market data: The Rio Times
This article was produced by The Rio Times’ automated AI newsroom. Editorial responsibility: Matthias Camenzind, Publisher and Editor-in-Chief. The Rio Times also runs Ask Rio Times, which answers from 100,000+ of our own articles, the daily Latin America Power Map, and prediction-market odds on elections and markets.. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.