Global Economy Briefing: US 10-Year Yield Hits 5.24%, Gold Falls 3.7%
Global economy briefing: the US 10-year yield closed at 5.244%, a high since 2007, gold fell 3.71% to US$4,127 and Fed hike bets rose. What to watch today.
Rio Times Global Economy Briefing
Updated 1 time · Latest: 29 September 2026
The Big Three
- Higher-for-longer returns to the bond market The US 10-year yield closed at 5.244%, its highest since 2007, while markets priced roughly a 70% chance of another Federal Reserve hike in October. Rising yields lift the dollar’s appeal and raise the funding cost for Latin America.
- Gold loses its defensive shine Spot gold fell 3.71% to US$4,127 an ounce as Treasury yields and expectations of further Fed tightening increased the opportunity cost of holding bullion.
- Brazil’s easing cycle meets hotter inflation Brazil’s central bank cut the Selic by 25 basis points to 13.75% on 16 September, its fifth consecutive reduction. Mid-September IPCA-15 inflation then accelerated to 4.47% a year, just below the 4.5% ceiling of the target range.

United States
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
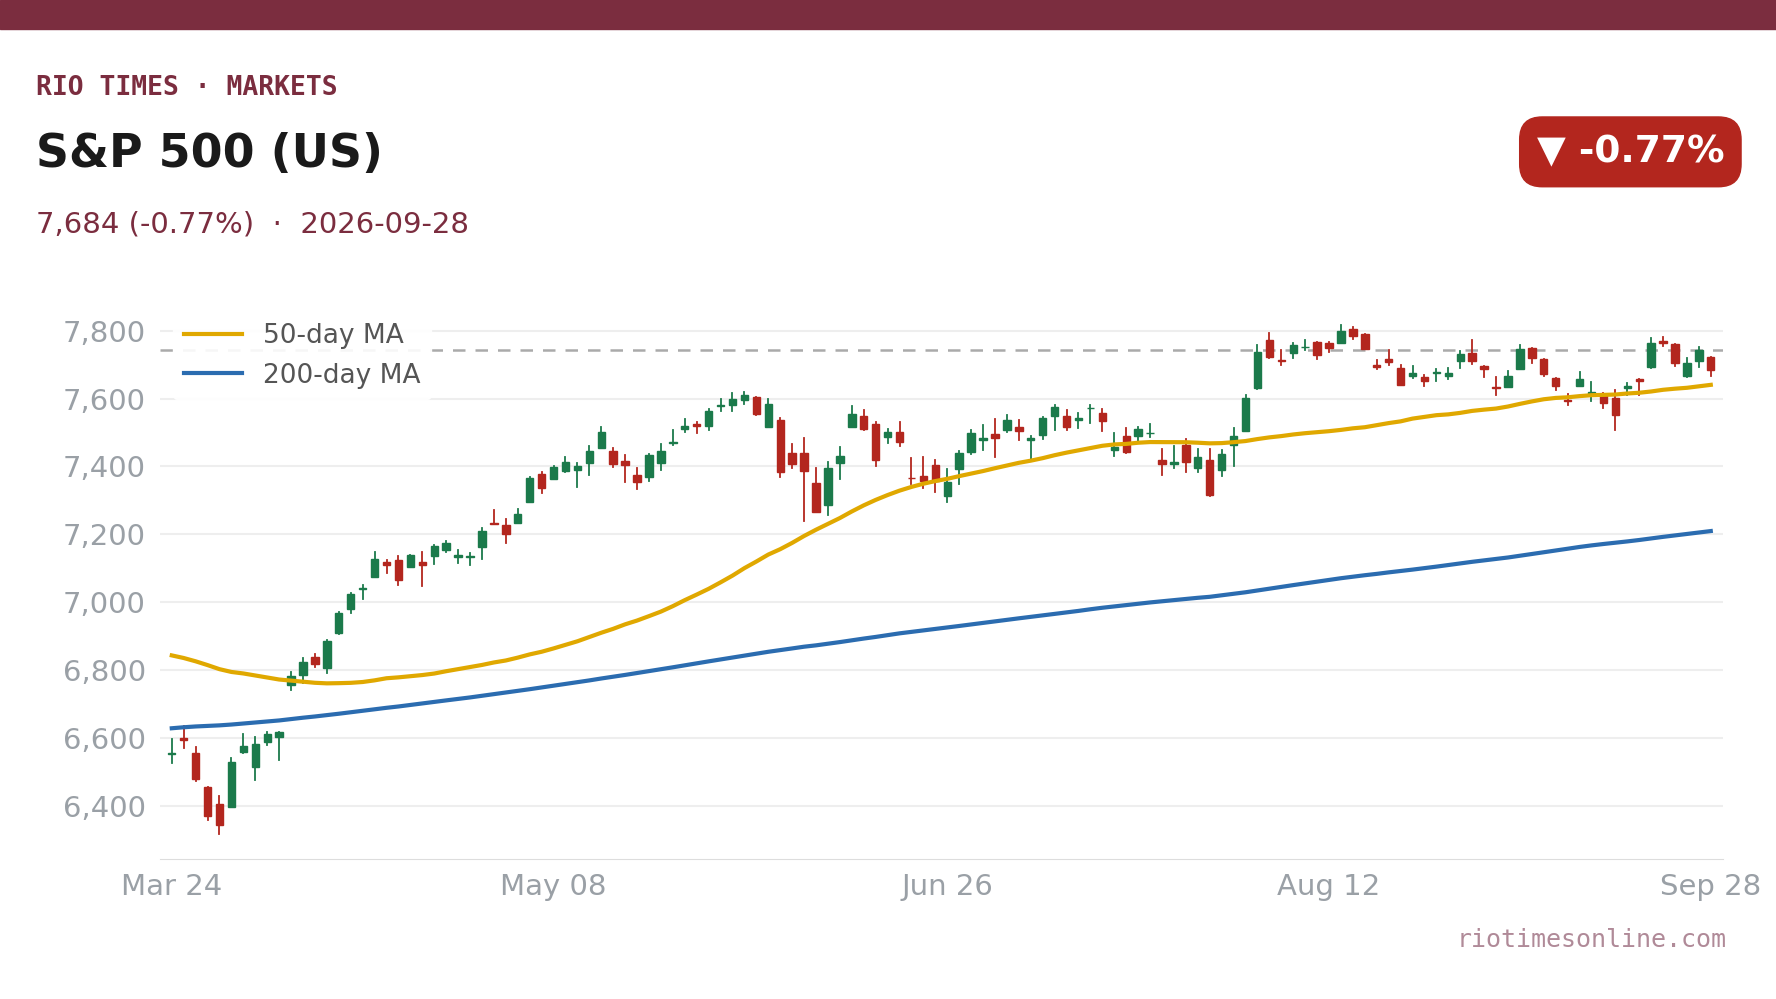
| S&P 500 | 7,684 | 7,743 | Lower |
| Nasdaq Composite | 26,820 | 27,069 | Technology leads declines |
| US 10-year yield | 5.244% | 5.165% | Yield climbs |
| Dollar index | 101.197 | 100.971 | Dollar strengthens |
Europe & United Kingdom
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| FTSE 100 | 10,685 | 10,695 | Slightly lower (−0.10%) |
| Euro STOXX 50 | 6,301 | 6,303 | Flat (−0.02%) |
| Spain September CPI (consensus) | 4.7% y/y | 4.3% | Flash estimate due today |
Latin America
| Indicator | Actual | Prior | Verdict |
|---|---|---|---|
| Brazil Selic rate | 13.75% | 14.00% | Fifth consecutive cut |
| Brazil IGP-M inflation (consensus) | 1.60% m/m | -0.22% | Due today; rebound expected |
| Colombia interest rate (consensus) | 12.00% | 12.00% | Decision Wednesday; hold expected |
| Chile unemployment (consensus) | 9.5% | 9.5% | Due Wednesday |
| Instrument | Level | Session |
|---|---|---|
| S&P 500 (US) | 7,684 | -0.77% |
| Ibovespa (Brazil) | 182,991 | -0.26% |
| USD/BRL | 5.2255 | +0.86% |
Source: RT live market data, close of Monday 28 September 2026.
Today’s Economic Calendar — Tuesday, September 29, 2026
| Time (GMT) | Country | Event | Consensus | Prior |
|---|---|---|---|---|
| 03:35 | JP | 40-Year JGB Auction | — | 3.865 |
| 05:00 | JP | Leading Index | 1.7 | — |
| 05:00 | JP | Coincident Indicator | 1.7 | 0.6 |
| 07:00 | DE | Bundesbank President Nagel Speech | — | — |
| 09:00 | CN | Current Account | 195.1 | 184.3 |
| 10:00 | DE | Bundesbank Nagel Speech | — | — |
| 10:00 | DE | Bundesbank Mauderer Speech | — | — |
| 11:00 | BR | IGP-M Inflation | 1.6 | -0.22 |
| 11:30 | BR | Bank Lending | 0.5 | 0.3 |
| 12:00 | BR | Unemployment Rate | 5.3 | 5.3 |
| 12:55 | US | Redbook | — | 7.6 |
| 13:00 | US | House Price Index | 2.2 | 2.3 |
| 13:00 | US | House Price Index | 442.9 | 442.5 |
| 13:00 | US | House Price Index | 0.1 | — |
| 13:00 | US | S&P/Case-Shiller Home Price | 2.2 | 2.1 |
| 13:00 | US | S&P/Case-Shiller Home Price | 0.2 | 0.4 |
| 14:00 | US | JOLTs Job Openings | 7.24 | 7.271 |
| 14:00 | US | CB Consumer Confidence | 90 | 89.4 |
Live Market IntelligenceGlobal Markets — Live Board
Rio Times · Live Market Intelligence
Global Markets — Live Board
| Instrument | Last | Change | YoY | Prev. | High | Low | Volume |
|---|---|---|---|---|---|---|---|
| SPX | 7,751 | +0.29% | — | — | — | — | — |
| NDX | 29,799 | +0.93% | — | — | — | — | — |
| DJI | 53,810 | +0.03% | — | — | — | — | — |
| RUT | 3,041 | +0.46% | — | — | — | — | — |
| US10Y | 4.6760 | -0.17% | — | — | — | — | — |
| VIX | 14.60 | -4.45% | — | — | — | — | — |
| DAX | 26,331 | -0.23% | — | — | — | — | — |
| FTSE | 10,833 | -0.10% | — | — | — | — | — |
| CAC | 8,675 | -0.46% | — | — | — | — | — |
| STOXX | 659.48 | -0.16% | — | — | — | — | — |
| NIKKEI | 67,524 | +0.83% | — | — | — | — | — |
| HSI | 25,440 | -0.83% | — | — | — | — | — |
| KOSPI | 6,579 | +3.68% | — | — | — | — | — |
| CSI300 | 4,691 | +0.58% | — | — | — | — | — |
| NIFTY | 24,436 | -0.15% | — | — | — | — | — |
| TSX | 36,619 | +0.39% | — | — | — | — | — |
| GOLD | 4,461 | +1.78% | +33.20% | 4,383 | 4,503 | 4,421 | 139,824 |
| SILVER | 65.59 | +1.26% | +73.05% | 64.77 | 66.98 | 64.81 | 46,406 |
01 The bond market sets the temperature
Equities softened as the rise in US yields challenged the valuation premium of risk assets. The S&P 500 fell 0.77% to 7,684, while the Nasdaq slid 0.92% to 26,820.
The squeeze was clearest in gold, which dropped 3.71% to US$4,127 an ounce as investors favoured income-bearing Treasuries and a firmer dollar. The VIX jumped 8.07% to 16.07, signalling renewed caution.
For Latin America, the combination is uncomfortable: a stronger dollar can pressure local currencies, while higher US yields reduce the room for central banks to ease without reviving imported inflation.
02 Monday’s data, one by one
China industrial profits (NBS, January–August): up 15.7% year on year to 5.27 trillion yuan (about US$786 billion), below the 18% forecast and slower than 17.6% for January–July. August alone rose 4.2%, held back by a high base a year earlier. Electronics profits more than doubled and supplied 62% of the growth, while utilities fell 12.0%. Momentum is fading outside AI-linked sectors; markets barely reacted.
Dallas Fed manufacturing index (September): the headline business activity index eased to 9.8 from 11.6 in August but beat the forecast of 1. Output jumped 13 points to 29.5, and raw-material prices rose to 52.2 (average 28.0). Texas factories are growing faster and paying more, which strengthens the case for another Fed hike.
US Treasury bill auctions: the 13-week bill sold at 4.110%, up from 4.015% a week earlier, and the 26-week at 4.285%, up from 4.155%. Short-term money is pricing more Fed tightening.
Fed speakers: Vice Chair for Supervision Michelle Bowman spoke on bank stress testing and gave no rate signal. Richmond Fed President Thomas Barkin’s fireside chat produced no published text. Governor Lisa Cook said inflation was an estimated 3.8% in the year to August (3.4% core) and that she will “consider what policy rate may be needed”. The 10-year yield added 7.9 basis points to 5.244%.
Europe: the euro-area calendar carried no major releases. At the European Parliament, ECB President Christine Lagarde said the ECB sees “higher inflation ahead but no signs yet that it is becoming embedded”, calling a “measured response” appropriate. The Euro STOXX 50 was flat (−0.02%).
Latin America: Brazil’s Focus survey raised 2026 inflation expectations to 4.99% from 4.92%, with the Selic seen at 13.50% by year-end. Brazil’s August current-account deficit was US$5.05 billion, against about −US$4.9 billion expected (July: −US$9.37 billion), and direct investment inflows reached US$7.40 billion, against about US$6.9 billion expected. Mexico posted an August trade surplus of US$605 million (INEGI) after a US$848 million deficit in July, against forecasts ranging from a small deficit to a US$1.4 billion surplus. The real weakened 0.86% to 5.2255 per US dollar and the Mexican peso 1.74% to 17.99.
03 The Fed’s next move is back in the price
Monday’s firmer Dallas Fed survey and Cook’s warning of continued inflation pressure helped push markets to price roughly a 70% probability of another 25-basis-point Fed hike at the 27–28 October meeting. The dollar index edged up 0.22% to 101.197.
The backdrop raises the bar for Brazil and peers. Brazil’s Selic cut to 13.75% narrows the interest-rate cushion against dollar strength just as mid-month inflation climbs towards the 4.5% ceiling.
Fed speakers due today include Bowman, Goolsbee, Musalem, Williams and Waller. Their tone will shape whether the October meeting stays live or cools.
04 A crowded data runway
Tuesday’s calendar brings US job openings and Conference Board consumer confidence, Brazil’s IGP-M and unemployment figures, and Spain’s flash September inflation.
Wednesday is busier. The US publishes PCE inflation, the final second-quarter GDP estimate, EIA crude stocks and quarterly grain stocks. Chile reports unemployment, retail sales and industrial production, and Colombia’s central bank decides on rates.
Brazil’s budget balance and debt ratios also land on Wednesday. Net debt previously stood at 69.1% of GDP, and gross debt is expected at 83.1%, up from 82.5%.
Brazilian assets face a two-sided test: domestic inflation argues for caution on further cuts, while global yields and the real-dollar exchange rate transmit the Fed’s policy to local financial conditions.
What to watch today and this week
- Wednesday: US PCE inflation and the final second-quarter GDP estimate; Colombia’s rate decision.
- Friday: US September employment data; investors will assess the case for an October Fed hike.
- Next week: Fed speakers and the run-up to the 27–28 October policy meeting remain the main global rates catalyst.
- Ongoing: Brazilian inflation, the Selic path and the real, at 5.2255 per US dollar on Monday.
Frequently Asked Questions
Why did gold fall?
Higher Treasury yields, a firmer dollar and increased expectations of Fed tightening reduced demand for non-yielding gold.
What is driving US yields?
Markets increased the probability of another Fed hike, while resilient US growth kept pressure on rates.
What happened to Brazil’s Selic?
The central bank cut it by 25 basis points to 13.75% on 16 September, but mid-month inflation edging towards the 4.5% ceiling complicates the path ahead.
How does a stronger dollar affect Latin America?
It pressures local currencies and can push up imported inflation, narrowing the room for regional central banks to cut rates.
What should investors watch today?
Fed speakers, US job openings and consumer confidence, and Brazil’s IGP-M and unemployment data. US PCE inflation and Colombia’s rate decision follow on Wednesday.
This article was produced by The Rio Times’ automated newsroom system. How we use AI · Report an error
LatAm Markets: Live Signals → — real-time movers, turnover leaders and FX across Latin America.